

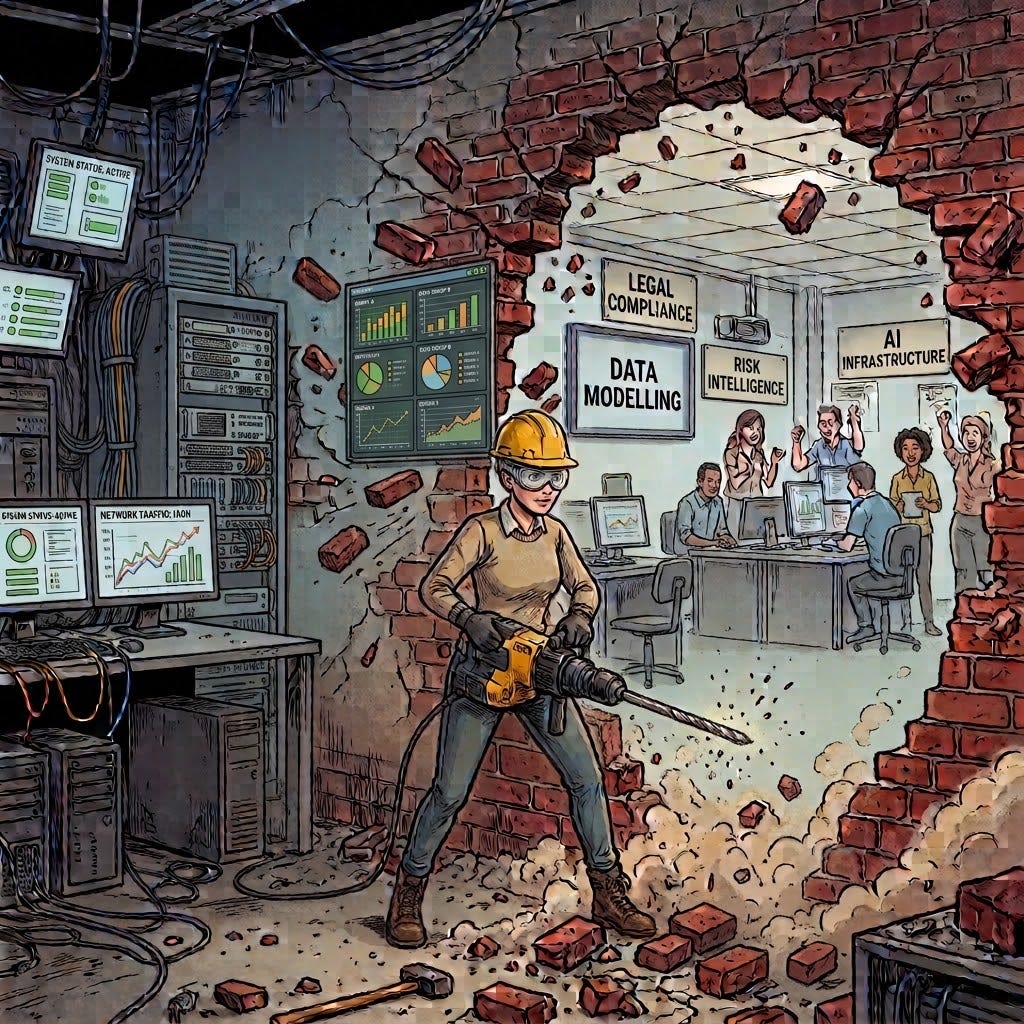
Over the last couple of weeks, FPC spoke with a recently exited European ad tech founder and a soon-to-leave-company big ad tech hitter about new startup endeavours. Both told FPC they are working on new startups in “adjacent ad tech” categories.
Adjacent ad tech (AAT) is a trend we are seeing more of, as new startups look to build their own categories and become the monopoly of one - breaking new ground in an industry over-optimised for one giant media market. What is adjacent ad tech, and what is the rationale for building an AAT solution?
America Is Still “Home Of Scale”
It would be stupid and feckless to write off a go-big-or-go-home US play. The numbers don’t lie. The exits don’t lie. It’s the world’s biggest homogenised ad market. Even with extreme walled garden penetration, the open internet is still massive in the US.
You can eke out a great living and more easily reach £100 million in revenue, even with an under-the-radar, me-too, somewhat undifferentiated product.
The buy-side economics are hard to ignore. There are over 4000 indie agencies in the US - many of which easily outspend regional holdco agencies in Europe. You can follow the well-trodden route of greats like MIQ and go regional first, avoiding painfully expensive New York and LA hires. Indies in the US are open to testing - so opportunities abound for good ad tech.
If you intend to go to the US, get raising (big cheques are required). Scale is possible. Look at the enormous Vibe exit recently. Ultimately, the probability of success is much lower than your US peers. Along the way, it really is a game of luck. For every stellar Vibe success, there are 100 failures. It’s not down to a shit product, but to inherent barriers in competing in the US.
Optimising To The US: The Inherent Structural Disadvantages
When deciding to optimise your solution for the US, keep a few things in mind. First, consider money. US ad tech can raise more money than you. In some cases, that might not always be true. French VCs always seem to have money for French ad tech looking to have a go. But for the rest of European and ROW ad tech, it’s not so simple.
FPC has seen it first-hand: US startups have access to an infinitely larger pool of capital. It gives them an inherent advantage. This is not a gripe - just a reality.
Structural issue number two: your US peers are based in the US. They don’t have to worry about the bureaucracy of obtaining a visa or the mental torture of moving family to the US. That’s a lot to deal with when you are going to the mat every day to win market share.
The third structural issue is: network. Every great ecosystem is shaped by its influencers and decision-makers. The US has key individuals you need onside. If you don’t win hearts and minds, you will be starved of the ad tech publicity oxygen you need to gain adoption. This is critical as you look to get visibility in competitive categories.
Arthur Querou absolutely nailed this, becoming a living ad tech folk hero with his antics. It helped the profile of the company - and definitely got him on the radar of every major corp dev team.
‘Tis But an Ad Tech Scratch
We have been observing this market reality for some time and have optimised how we invest accordingly. Continuing with the same US-at-any-cost strategy would be a definitive lose-lose for everyone. The structural issues above (funding, location and embedded network) limit exit opportunities.
It’s not that we wouldn’t have outcomes; it’s just that the US-or-bust gambit has a lower chance of financial success overall. And ultimately we want to make money for our LPs and ourselves.
Rare exceptions exist, of course. Bedrock Platform (an incubation from Fund 1), for instance, just invented its own ad tech category - Composable Buying Platform (CBP) - disrupting the current tech infrastructure supply chain. It is upending established industry norms and taking a chainsaw to eye-watering ad tech taxes. The company is on a serious trajectory. It’s having its “Invite Media” moment - and a seismic reordering event in the ad tech ecosystem is underway.
Bedrock aside, it is hard to justify a face-off with better-funded US companies in their own backyard. It’s akin to the Black Knight fighting King Arthur in Monty Python’s Holy Grail. The Black Knight loses a number of limbs in a one-sided broadsword fight with Arthur - but still believes he can win.
He shouts, “’Tis but a scratch”, as he aimlessly throws his armless torso around the place. In this instance, The Black Knight is very much non-US ad tech - outmanoeuvred and outmatched by a better-funded and more connected US peer. Maybe instead of Monty Python, we should be building strategy around ad tech Sun Tzu. Effectively, fight a competitive battle on your own terms. As we pointed out in a previous post, most ad tech is optimised for the US. Why does it have to be so?
Ad Tech Adjacency Is Just Innovation Writ Large
You are rightly asking now: what is ad tech adjacency? From an FPC perspective, it’s finding areas where a localised or verticalised competitive advantage is built in.
In this part of the world, areas like legal / data compliance, risk intelligence, data modelling, verticalised media, and sovereign infrastructure are obvious opportunities, with large, untouched commercial markets attached.
If you zoom out, you could conclude that all we’re really doing with AAT is innovating. America is just one giant pool of ad spend. It does what it does. And there is nothing wrong with that - if it ain’t broke, don’t fix it.
It’s just not a great use of effort, time or capital for a non-US fund that must think differently because of the aforementioned structural constraints. Who in their right mind would want to bring a rusty blunt butter knife to a tank fight? Certainly not FPC.
Ironically, US Ad Tech Buys AAT
If you have read up to this point, you’ve discerned a clear, emerging fund thesis: incubating new ideas around a localised and verticalised (but scalable) ecosystem. The buyer of the majority - if not all - will be large US ad tech firms and strategics.
Surprised? You really shouldn’t be. It’s logical for US companies to buy new revenue globally, outsourcing R&D to seasoned local operators who instinctively understand non-US geographies. As we pointed out earlier, why would US ad tech conceive of new categories outside the US that require nuanced development, risk-tolerant investment and specialised teams to build?
As part of Fund 2, corporates can co-incubate new ad tech ventures with FPC, shape them around their own strategic gaps, and then co-invest alongside Fund 2 to take equity, preferred access, and implicit first look at acquisition.
All that is couched around our ability to incubate and scale native ad tech businesses that can thrive and survive outside the US.
We build and scale them. US ad tech buys them. We are seeing that play out right now.
FPC currently has 6 incubations in production at various stages - from nascent risk intelligence and legal compliance platforms to revenue-generating AI infrastructure.
There has never been a better time to build new ad tech solutions. FPC is focusing hard on the AAT opportunity. We are looking for smart corporates and co-investors to help build and fund it. As ever, get in touch if you want to learn more about our incubations and where the hotspots are in the industry. And on that epic note, we will leave it there for the week.